








Where mining is allowed, and how the income is treated
Most countries neither welcome nor ban mining: they tax it, license it or make banking hard. The three states a country can be in, and how income is taxed.
Is this legal or tax advice?
No. This is not legal or tax advice, and an article cannot give it. Rules differ by country and change with little notice. They often depend on facts about you that general writing cannot know.
What follows is the shape of the question and where the real answers live. Then you know what to ask, and whom to ask.
One thing does apply everywhere: check the rules before you buy hardware, not after. Every expensive version of this story starts with equipment that was already paid for.
Is mining legal in your country?
People ask this as if the answer were yes or no. In practice a country is in one of three states, and nearly everybody lives in the middle one.
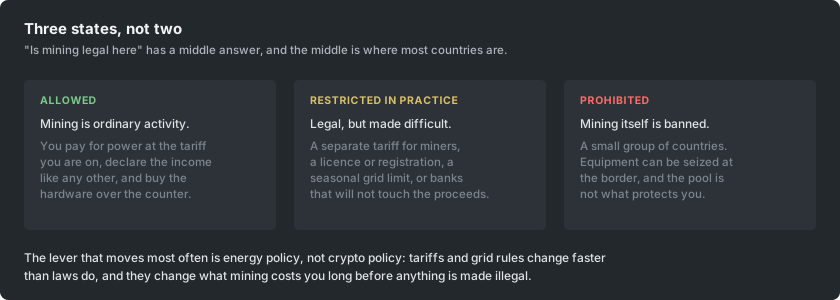
- Allowed: mining is ordinary activity. You buy hardware over the counter, pay for power on a normal tariff and declare the income like any other.
- Restricted in practice: mining is legal, but something else makes it hard.
- Prohibited: the activity itself is banned, in a small number of countries. China has banned mining since 2021, and the ban has held.
The middle state is where the interesting problems are. The obstacle can be a separate, more expensive tariff for miners. It can be a registration or licence requirement, or a seasonal restriction when the grid is stressed.
Or banks may refuse to process the proceeds, even though holding coins is lawful.
What is most likely to change your mining costs?
Watch the electricity regulator rather than the financial one. Tariffs, connection rules and seasonal curtailment change far more often than laws do. Curtailment means large loads being told to switch off when the grid is under strain.
These changes need no new legislation. They can make mining uneconomic without making anything illegal.
This has already happened in several places, at both national and regional level. It took the form of moratoriums on new mining connections, tariff classes just for mining and seasonal shutdowns during peak demand.
None of those is a ban. All of them end the same way for the person paying the bill.
How is mining income taxed?
Almost every tax system that has addressed mining treats it as two separate events:
- The coins arriving, valued in your own currency at that moment.
- The later sale or swap, measured against that first value.
The dedicated article on mining and tax covers what to record. It also explains why keeping the record is harder than the rule.
Systems differ in their rates and their framing. A few large markets show how differently the same activity can be treated. They illustrate the range and are not a checklist, so confirm each one with its own tax authority before you rely on it.
- United Kingdom: mined coins are income at their value when received. A later disposal is looked at separately under capital gains rules.
- Germany: mining and similar rewards are income. The country is unusual in how favourably it has treated long-held assets on disposal.
- India: a flat rate applies to crypto gains, with tax withheld at source on transfers. Losses on one asset cannot offset gains on another, which changes the arithmetic of an unprofitable year.
- Australia: rewards are ordinary income at their value when received. A discount is available on gains from assets held beyond a year.
- Japan: digital assets have been moving toward a separate flat regime rather than ordinary income rates. The change is being phased in.
The pattern is the same in all of them. Receiving the coins is an event for tax, whether or not you sell.
The size and organisation of the operation decide whether it counts as a hobby or a business. That in turn decides what you can set against it.
What should you check before you spend money?
- Is mining itself lawful where you are? Is there a registration or licence step?
- Is there a tariff class for mining, or a rule against running commercial load on a residential connection? This one catches people who assumed the household rate applied.
- Can your bank receive the proceeds? In some markets the coins are legal and the banking is the obstacle.
- What happens at the border when hardware arrives? Is mining equipment treated differently from ordinary computer parts?
- What do you owe when coins arrive, not just when you sell? What records does the authority expect?
Where can you find the real rules?
Go to the primary sources. They are free and more current than any summary.
- Your national tax authority. In most countries it publishes its own guidance on crypto assets.
- Your electricity regulator or utility. It publishes the tariff schedule, the document that decides most of your mining economics.
- The issuing body, where a licence exists. It lists the requirements.
Country-by-country tables online help you get your bearings, but they are unreliable for decisions. They go out of date quietly. This subject changes so often that out of date is their normal state.