








Mining and tax: what to record, and why that is hard
Mining income is usually taxed at two moments. Learn what each one is, why hourly payouts make records hard, and exactly what to keep.
What this article can and cannot tell you
This is not tax advice, and it cannot be. Rules, rates, thresholds and definitions differ by country. They also change over time.
How they apply depends on facts about you that an article cannot know. What it can do is show the shape of the question. Then you can meet somebody qualified with the right records, not a year of guesses.
The one universal piece of advice is at the bottom: start keeping records now, not in filing season. The details are easy to collect as they happen. They are close to impossible to rebuild afterwards.
The two taxable moments: receiving and selling
Almost every tax system that covers mining treats it as two separate events. Mixing them up is the most common mistake miners make.
- Receiving. The coins arrive and become yours. Most systems treat this as income. It is measured by what the coins were worth in your own currency at that moment.
- Selling, swapping or spending. This is a separate, later event. What matters is the difference between what you get and the value the coins had when you received them.
Holding, however long, is not usually an event by itself. The price moving while you hold is not the point. What counts is what you do at each end.
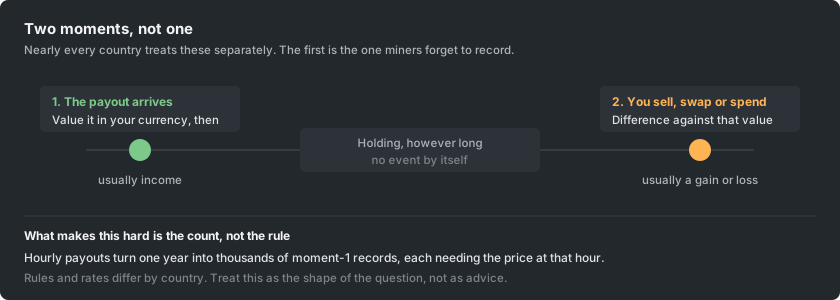
Why hourly payouts make the records the hard part
The rule fits in one sentence. Applying it does not, because of the payout schedule.
A pool that pays hourly creates a receipt event every time it pays you. Over a year that is thousands of them. Each one needs the value of that amount, of that coin, at that hour, in your currency.
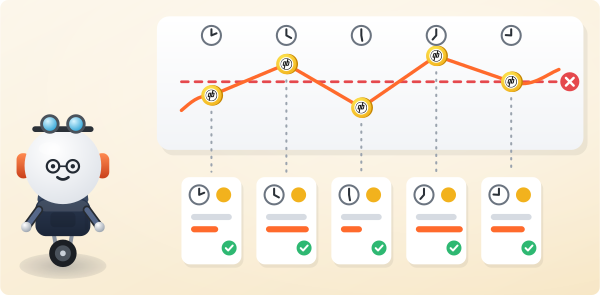
Nobody rebuilds that from memory in April. Using one price for the whole year is wrong, and anyone who checks can see it.
This is the practical case for collecting as you go, and it is why tools for this exist at all. Whatever you use needs the same inputs. They are all available while the payouts happen.
What records to keep
For each payout you receive, keep:
- The date and time it arrived.
- The amount and which coin it was.
- What that amount was worth in your own currency at that time.
- The transaction id, and the wallet address it went to.
Separately, for the year as a whole, keep:
- What you paid for the hardware, and when.
- The electricity used for mining. This is much easier to defend if the rigs have their own meter.
- Pool fees and any miner developer fee. Both come out of what you were credited.
- Every later sale, swap or spend of mined coins, with the same fields as above.
Where to find these numbers on this pool
Your payments page lists every payout with its timestamp, amount and transaction id. Your dashboard carries the same per-worker history.
The public API serves the same records to programs and spreadsheets. It is the practical route if you have too many payouts to copy by hand. The API reference documents the endpoints and their fields.
The pool does not hold one number: the price in your own currency at each payout time. That comes from a price source you and your accountant agree on, applied consistently.
Consistency matters more than which source you pick. Switching sources mid-year is the thing that is hard to explain.
Is your mining a hobby or a business?
Most systems separate mining as a personal activity from mining as a business. The difference changes both what you owe and what you can deduct.
Where the line sits varies, but the questions asked are similar:
- How organised is it?
- How much is at stake?
- Is it run in a way that looks intended to make a profit?
- How much of your time does it take?
Here are two examples, offered as examples and not as a full list.
- United States: mined coins are ordinary income at their value when received. When the activity amounts to a trade or business rather than a hobby, it counts as self-employment. That brings its own additional tax.
- United Kingdom: the question is whether the activity amounts to a trade at all, using long-standing tests. Where it does not, the value you received is still taxable as miscellaneous income. Later disposals are looked at separately again.
The pattern is the same in both, and in most other countries. A bigger, more deliberate operation is treated more like a business. More can be set against the income, and more obligations come with it.
The most common record-keeping mistakes
- Nothing recorded at receipt. This is the most expensive mistake. The second event cannot be worked out without the first, and by then the prices are historical.
- One price for the whole year. It is convenient, wrong, and visibly wrong.
- Only the sale is declared. The income at receipt is a separate event. It does not disappear because you have not sold.
- Mining coins and personal coins in one wallet. Untangling where coins came from, years later, is what every adviser on this warns about. Use a separate wallet or account for mining from the start.
- Deductions with nothing behind them. Electricity and hardware are often deductible in some form, but only with something to show. That is why the separate meter is worth the trouble.
- Assuming small means exempt. Many places have thresholds. They usually decide whether you must file, not whether the income counted.
The one recommendation
Get the records right now. Then ask somebody qualified in your own country what they mean.
The records are the part only you can produce. They cost almost nothing while the payouts arrive. Every professional you might hire will start by asking for the lists above.